Florida VA homebuying field guide
You served. Let’s make your benefit easier to use.
Straight answers for veterans, active-duty service members and military families from someone who comes from a proud Navy family.
Start with the benefit
A VA loan is powerful. Understanding it should not be difficult.
A VA loan is a mortgage backed in part by the U.S. Department of Veterans Affairs and made by an approved private lender.
Eligibility and available entitlement are confirmed, often through a Certificate of Eligibility. The lender reviews the borrower, property and loan under VA and lender requirements.
Learn about your Certificate of Eligibility →Your VA homebuying route
Four stops from questions to keys.
Every buyer’s path is different, but these are the conversations that help create a clear plan.
- 01Confirm
Check eligibility and entitlement
Request your Certificate of Eligibility and review any prior use of your VA benefit.
- 02Plan
Build the full mortgage picture
Review income, credit, debts, available funds and a payment that feels comfortable.
- 03Shop
Choose an eligible home
Connect the financing plan to the property, contract and VA appraisal process.
- 04Close
Stay informed through the finish
Know what is happening, what is needed and what comes next.
A personal reason
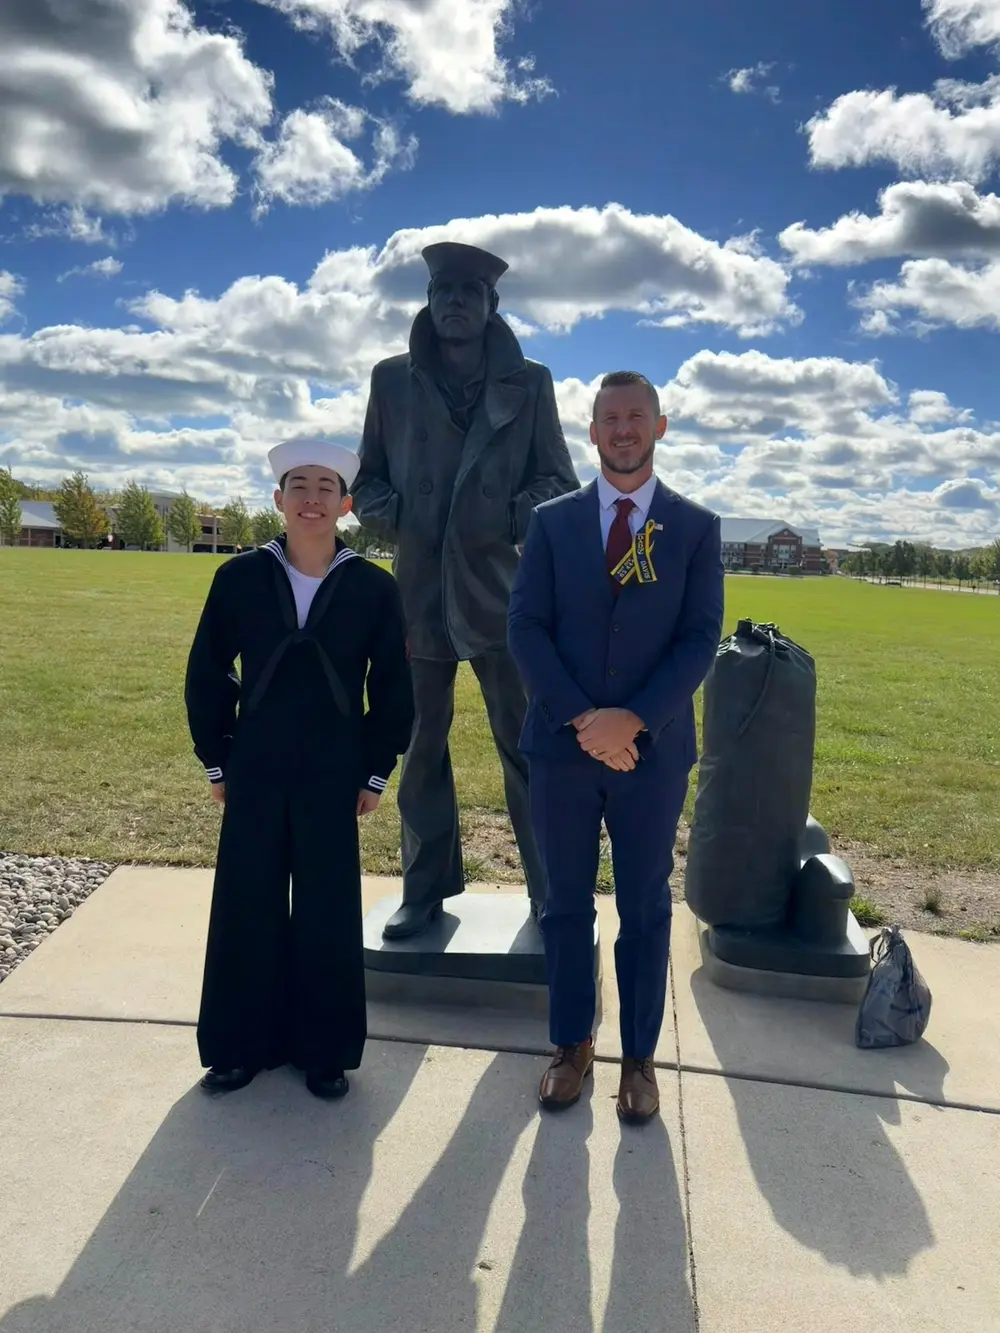
Military service is part of my family’s story.
My father served in the Navy, and my son followed that path. Helping military families understand the benefit they earned means more to me than checking a box on a loan application.
Meet RustyVA myth or fact?
Tap a card for the straight answer.
Mortgage myths travel fast. Good information should catch up.
Who might consider it?
Start with your situation.
This is general education, not a promise of eligibility. Your complete financial and property picture must be reviewed.
Eligible veterans and active-duty service members
Eligible National Guard and Reserve members
Certain eligible surviving spouses
Qualification considerations
What the review may include.
These are conversation points, not buttons. We will review each one as part of your complete mortgage plan.
VA eligibility and entitlement
Your Certificate of Eligibility helps confirm your service eligibility and available entitlement. Prior VA loans may also affect the review.
Ability to repay and acceptable credit history
The lender reviews income, monthly debts and credit history. VA eligibility alone does not guarantee loan approval.
Primary-residence occupancy
VA financing is generally intended for an eligible home you plan to occupy as your primary residence.
VA appraisal and property review
A VA appraisal reviews value and minimum property requirements. It is different from a buyer’s independent home inspection.
Questions about your benefit?
Talk through your VA options before you start shopping.
A short conversation can help you understand eligibility, possible cash needs and the next step without pressure.
Potential advantages
Why buyers may explore it.
- No down payment may be possible for qualified borrowers
- No monthly private mortgage insurance
- Flexible features designed for eligible military borrowers
Potential limitations
What deserves a closer look.
- A VA funding fee may apply unless the borrower is exempt
- The home must meet VA property requirements
- Eligibility does not guarantee loan approval
Common mistakes
Plan before they become surprises.
A few early questions can prevent last-minute stress.
Assuming VA can only be used once
Confusing the VA appraisal with a home inspection
Not checking eligibility and entitlement early
Frequently asked questions
Simple answers to common questions.
Can I use VA more than once?+
Many eligible borrowers can reuse the benefit. Entitlement and prior VA loan history must be reviewed.
Is a down payment always required?+
Qualified borrowers may be able to finance without a down payment, depending on entitlement and the transaction.
Who determines funding-fee exemption?+
The exemption is based on VA records and eligibility information.
Talk with a Loan Officer
You earned the benefit. Let’s make sure you understand how to use it.
Bring your questions. I’ll help you understand the tradeoffs and next steps.